Accountant checklist for a small expense ledger
Before sending expense data to an accountant, confirm the period, sources and exceptions. A short checklist catches more than a last-minute search through a folder. ReceiptBook can organize records and exports, but the accountant decides accounting and tax treatment.
Confirm the period and scope
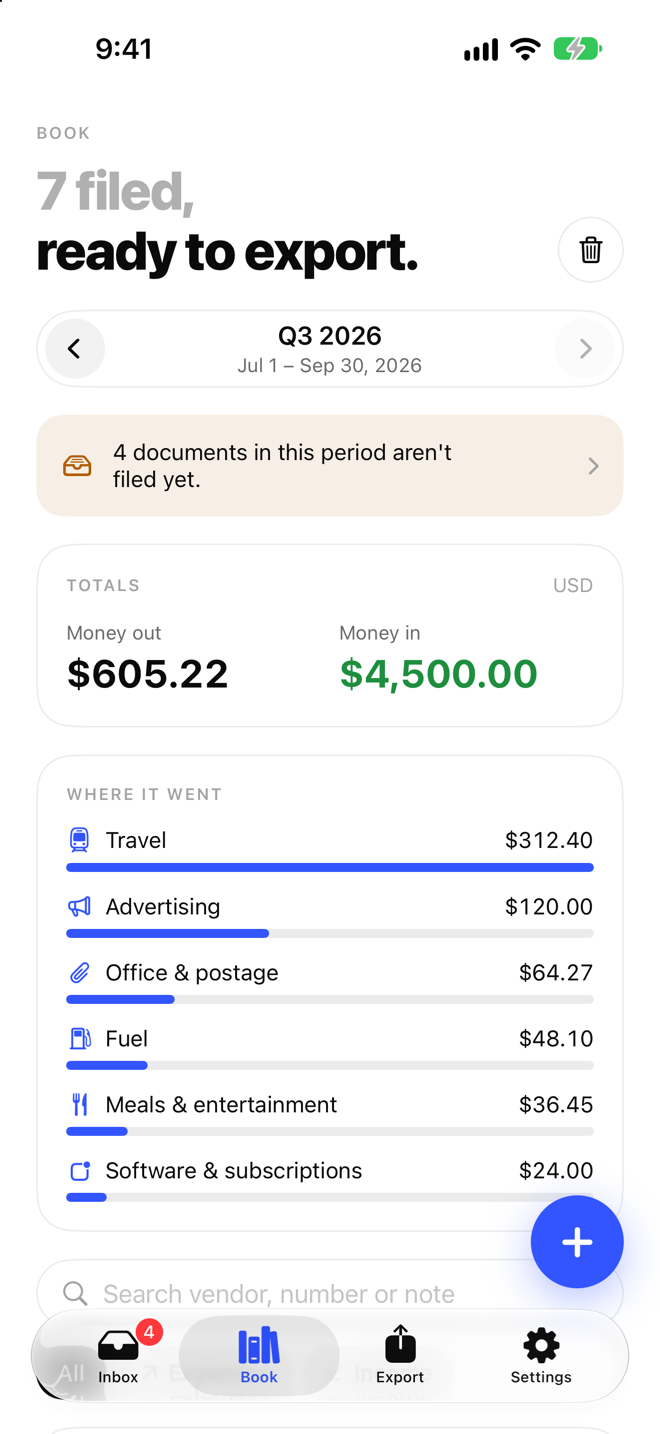
Write the entity, start date, end date, currency and tax year. Check late invoices, refunds, credit notes and transactions that belong to another period. Count records and compare the total with your source statements.
Check each record
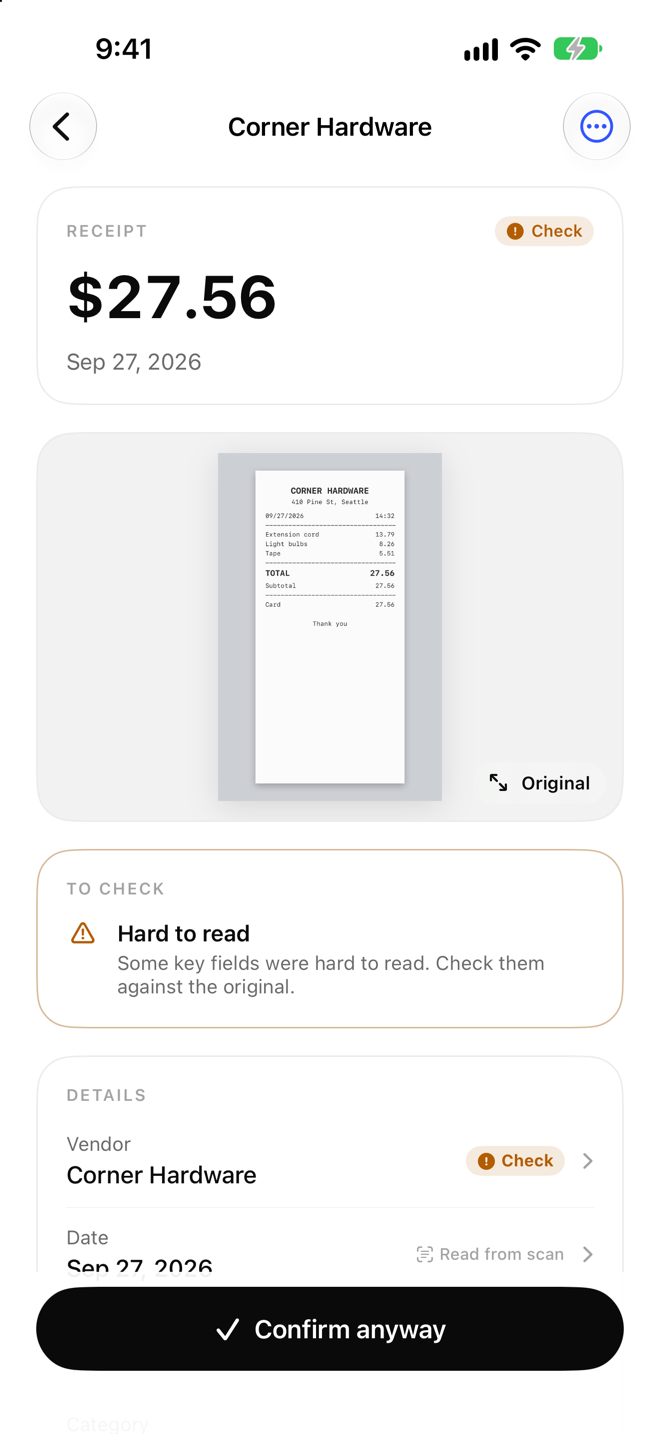
Review vendor, date, amount, currency, tax field, category and original file. Sample automated OCR and vendor rules rather than accepting every result without reading. Mark blurry, handwritten, mixed-use or incomplete records as exceptions.
Prepare the hand-off
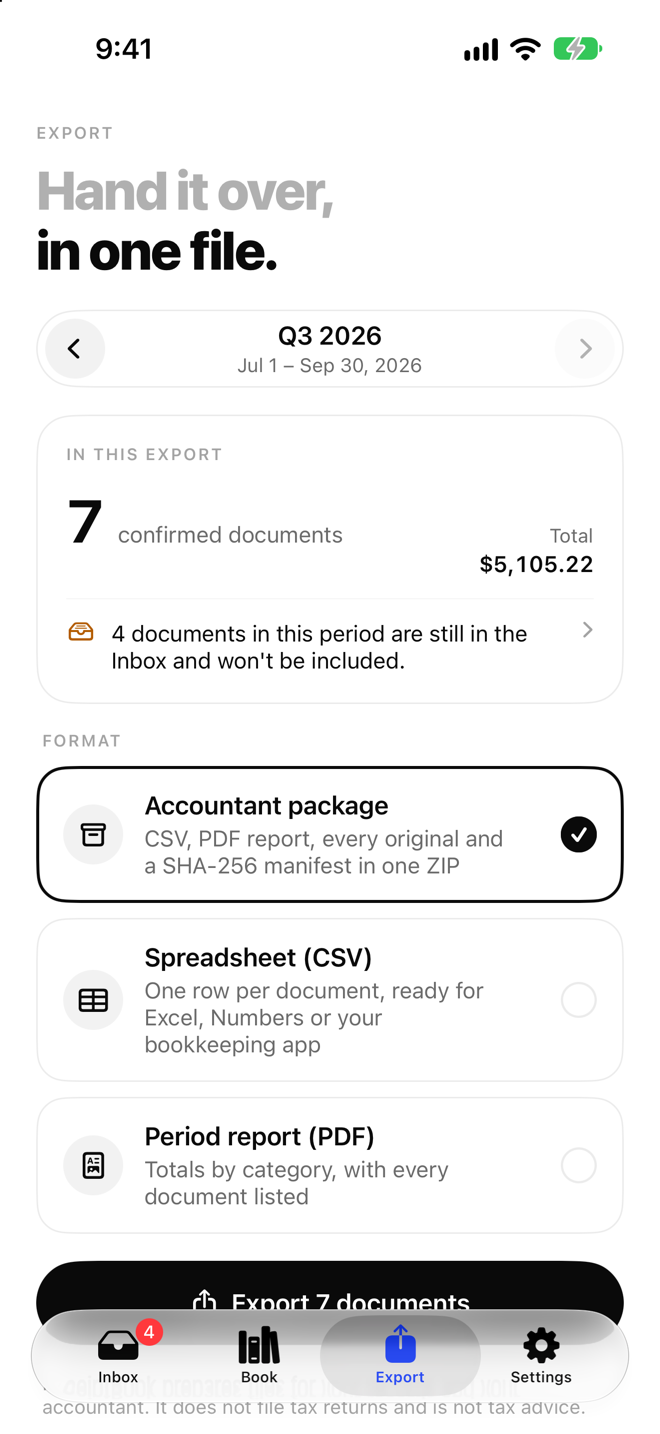
Create the required CSV, PDF, audit and manifest files, plus originals. See ReceiptBook. Open the files, verify encoding and page counts, and connect samples from summary to source. Keep the sent version unchanged.
Ask precise questions
List each question with record ID, amount, source and decision needed. Ask about VAT, mixed expenses, retention, currency conversion or missing documents instead of changing values to make a total look correct. Keep the answer with the package.
Note: This checklist supports preparation; it is not accounting or tax advice.
A practical workflow for this topic
When you search for “Accountant checklist for a small expense ledger”, the useful answer is usually a repeatable way to check the detail that matters. Use this ReceiptBook guide as a starting point, then confirm the current source before acting. The product can organize information and shorten a review; it cannot fill in missing facts or replace a professional decision.
Quick checklist before you act
- Keep the original receipt image available for review.
- Check merchant, date, amount, currency and category after OCR.
- Separate business, personal and tax-sensitive items instead of guessing.
- Export the original and the structured file together when handing records off.
Keep the decision traceable: record the version, date and source you relied on when the detail may change.
Detailed step-by-step workflow
This extended section turns “Accountant checklist for a small expense ledger” into a repeatable ReceiptBook workflow. The goal is not to create a longer checklist for its own sake. It is to make the important inputs visible, show what should be checked first, and leave a useful record of what was known at the time. That approach is especially helpful for receipt capture, OCR review, expense categories and structured exports. Read the steps in order the first time, then return to the relevant step when the situation changes.
Step 1: Define the question and the record you need.
Start with this action in ReceiptBook, then pause long enough to verify the result against the original source or observation. For “Accountant checklist for a small expense ledger”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Step 2: Gather the original inputs before interpreting the result.
Start with this action in ReceiptBook, then pause long enough to verify the result against the original source or observation. For “Accountant checklist for a small expense ledger”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Step 3: Review the result and record uncertainty or missing data.
Start with this action in ReceiptBook, then pause long enough to verify the result against the original source or observation. For “Accountant checklist for a small expense ledger”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Step 4: Save the version, date and next action for later comparison.
Start with this action in ReceiptBook, then pause long enough to verify the result against the original source or observation. For “Accountant checklist for a small expense ledger”, record the date, the relevant context and anything that was not available. A structured record is more useful when another person can understand what was checked without guessing what happened between two screenshots, notes or exports.
Quality checks and common mistakes
Long-form guidance is most useful when it explains the boundaries as well as the happy path. Before relying on a ReceiptBook record, run the checks below. They help separate a missing input from a negative result, an approximate value from a verified value, and a convenient summary from the original evidence.
Check 1
Do not start with the conclusion. Write down the question, the person or property involved and the time period first. In ReceiptBook, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 2
Do not mix old and new records without a date. Keep the original observation visible when you add a correction or update. In ReceiptBook, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 3
Do not treat a missing field as proof that the event, ingredient, expense or condition does not exist. In ReceiptBook, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 4
Do not share a polished summary before checking the original image, note, label, receipt or export behind it. In ReceiptBook, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Check 5
Do not use an app record as a substitute for a professional, medical, legal, financial or safety decision when the situation requires one. In ReceiptBook, keep the source, context and limitation close to the record so the next review can reproduce the decision.
Frequently asked questions
What should I verify before I rely on this guide?
For “Accountant checklist for a small expense ledger”, use ReceiptBook to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
What should I do when the information is incomplete?
For “Accountant checklist for a small expense ledger”, use ReceiptBook to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
How can I make the record easier to compare later?
For “Accountant checklist for a small expense ledger”, use ReceiptBook to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
When should I ask for another source or a specialist?
For “Accountant checklist for a small expense ledger”, use ReceiptBook to organize the observation and then verify the part that affects the decision. If a source, image, measurement or input is incomplete, mark it as incomplete instead of silently filling the gap. Add a date and a short note about the method used. When the consequence is important or the question sits outside the product’s purpose, confirm it with the current official source or an appropriate professional.
A practical review before you finish
Before closing this topic, read the title “Accountant checklist for a small expense ledger” as a question rather than a promise. Confirm the current version of the information, check the original evidence, and record the next action in ReceiptBook. A useful record says what was observed, when it was observed, what remains uncertain and who should review it next. This makes the article easier to apply today and easier to revisit when the facts change.
See the product in action